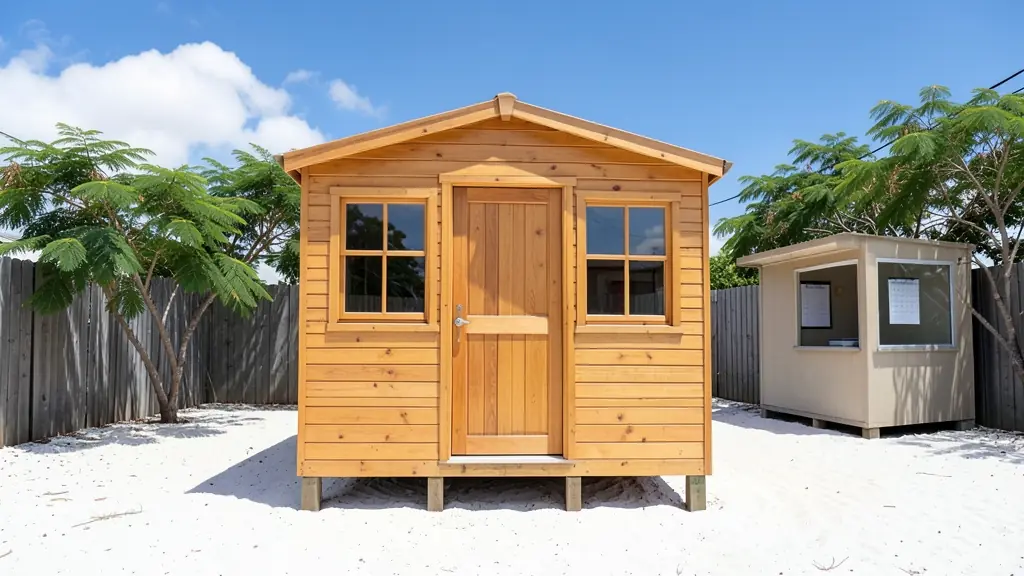
Many people searching for wendy houses on credit want a room or a home now and cannot pay the full amount at once. Suppliers offer a few ways around that: lay-by, monthly instalments or terms, and sometimes rent-to-own. They work very differently, and the monthly figure on an advert rarely tells you what you will pay in the end. We are not a lender and do not arrange credit. We can pass your request to suppliers who say they offer payment options, and they quote you directly.
Lay-by, instalments and rent-to-own
- Lay-by: you pay a deposit and then regular amounts, and the wendy is built or delivered once it is fully paid. It usually needs no credit check.
- Instalments or terms: the wendy may be delivered sooner and you keep paying afterwards. That is credit, and the seller or a finance partner is lending you money.
- Rent-to-own: you pay a monthly amount, and after an agreed period the unit may become yours. See wendy house rentals.
The National Credit Act and who is lending
A credit agreement in South Africa falls under the National Credit Act, and whoever gives the credit must be a registered credit provider. Ask the supplier directly whether they are registered with the National Credit Regulator, or who the lender is if a third party is involved. Nobody can honestly promise that you will be approved before they have assessed your application, so be careful of anyone who does, especially if they ask for a fee first. If your credit record is poor, lay-by is often the more realistic route.
Compare the total, not the monthly figure
A low monthly amount over a long period can add up to far more than the cash price. For each offer, ask for the cash price, the deposit, the number of payments, each payment amount, and any interest, fees or insurance. Multiply it out and compare totals. Then check what is included, using the same list you would for any wendy house price: size, plank grade, floor, delivery, erection and the base. A cheaper, smaller unit paid in cash sooner is sometimes the better buy (see cheap wendy houses).
Get everything in writing
Before you pay anything, get a written agreement that names the exact building and spec, the full amount, the payment dates, what happens if you miss a payment, and, for lay-by, what happens if you cancel or the supplier cannot deliver. Keep every receipt. Ask how long the supplier has been trading and whether you can see a unit they delivered. This is general information, not financial advice; for advice on your own situation, speak to a registered financial adviser or a debt counsellor.
What to put in your request
- The size and type of wendy or nutec house
- Whether you want lay-by, terms or rent-to-own
- The deposit you could pay up front
- The monthly amount you could manage
- Your area, for delivery and erection
Wendy Houses on Credit for homes, landlords, farms, schools and sites
- Homeowners: a 3 x 3 m room for a teenager paid on lay-by and delivered when paid up
- Landlords and backyard rentals: comparing the total cost of terms against saving for a second rental room
- Farms and smallholdings: a payment plan for workers' rooms spread over the months after harvest
- Schools, crèches and training centres: a crèche paying a classroom off on lay-by from fees, delivered before the new term
- Small businesses and home offices: a spaza room on terms from a registered credit provider, with the total in writing
- Construction and mine sites: rent-to-own site offices for a small contractor who will keep using them
- Guesthouses, campsites and resorts: a first guest cabin bought on lay-by before the holiday season
- Churches, clinics and NGOs: an NGO paying a storeroom off in instalments from donations, with written terms
- Builders, developers and installers: a builder who wants to know which suppliers offer lay-by for their own clients